
Law & Taxes
Real Estate Transfer Tax in Austria 2026: Purchases, Gifts and Inheritance
3.5 Percent or Progressive Rate? How Acquisition Types, Property Value and Previous Transfers Affect Austrian Real Estate Transfer Tax.
Short Answer
Real estate transfer tax in Austria depends on the type of acquisition and its tax base. In a standard purchase of real estate for consideration, it generally amounts to 3.5 percent of the consideration, subject at least to the property value. For acquisitions without consideration and preferential transfers within the family, a progressive rate generally applies to real estate. A gift or inheritance is therefore not automatically exempt from real estate transfer tax.
As of September 2026. The focus is on the direct acquisition of private residential property. Different rules may apply in part to agricultural and forestry land, company shares and business transfers.
Which Acquisitions Are Taxed?
The tax applies to certain legal transactions involving real estate located in Austria. This includes, in particular, a purchase agreement that creates a claim to transfer ownership. The tax therefore generally does not arise only when the transfer is registered in the land register. Conditions precedent and required approvals may affect the relevant date. The applicable provisions are Sections 1 and 8 of the Austrian Real Estate Transfer Tax Act.
Four questions are crucial for your preparation: Who is transferring the property to whom? What consideration is agreed? Which property value must be used? Have there been previous transfers that must be included in the calculation? A reliable tax calculation can only be made on this basis.
Purchase: 3.5 Percent of What?
In a typical purchase of an apartment from an unrelated person, the consideration is the starting point. It may include more than the monetary amount described as the purchase price in the contract. For example, assumed obligations may be relevant. For real estate, the taxable property value generally forms the minimum tax base. The distinction is governed in particular by Sections 4 and 5 of the Austrian Real Estate Transfer Tax Act.
Simple example: If the relevant consideration is EUR 420,000 and no higher minimum tax base applies, the real estate transfer tax amounts to EUR 14,700. Other acquisition costs are not included in this calculation.
A freely chosen low contractual value does not replace a tax-compliant tax base. In particular, have assumed debts, rights of residence and other benefits reviewed when structuring the contract.
Gifts and Inheritance: How the Progressive Rate Works
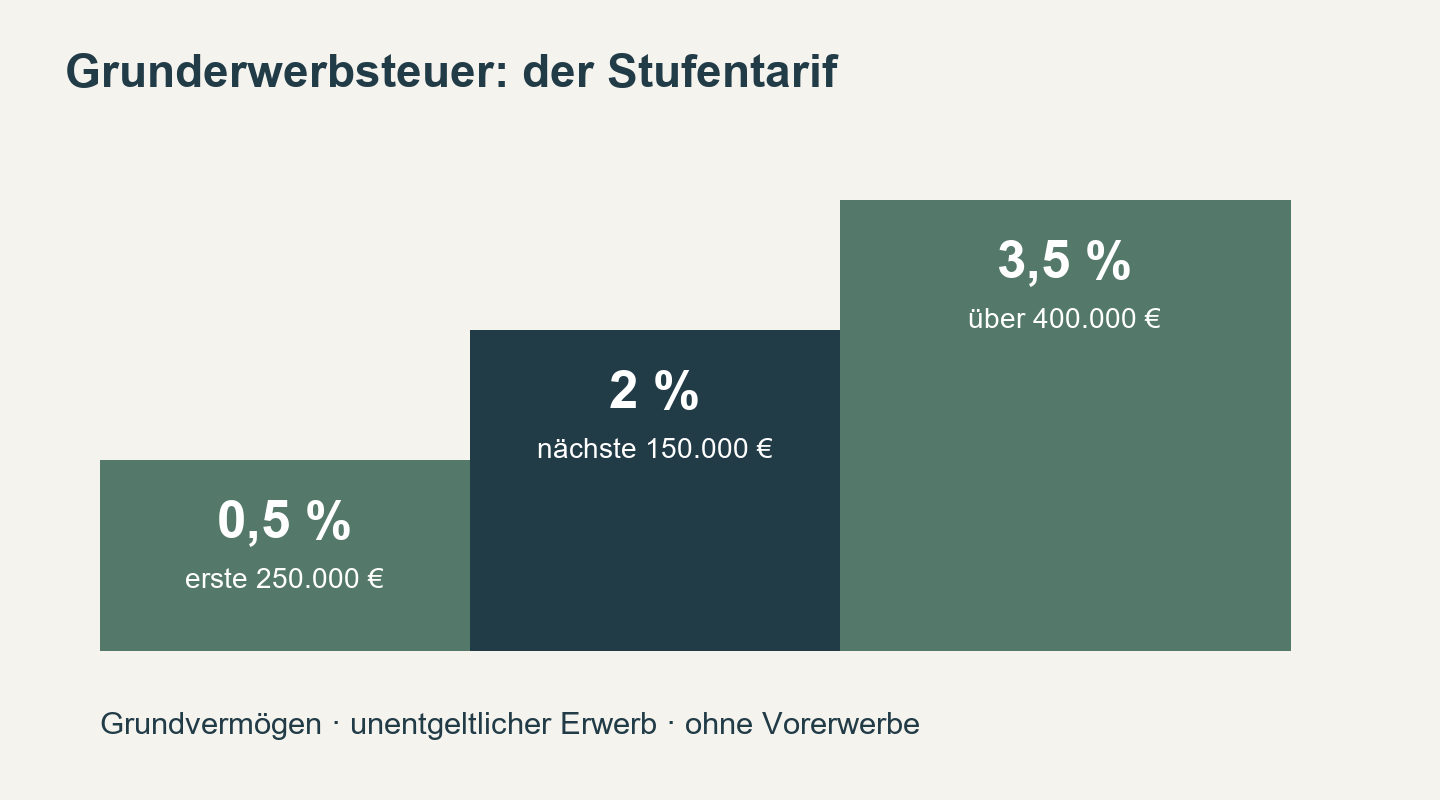
For acquisitions of real estate without consideration, the value components are taxed progressively:
| Portion of the property value | Tax rate |
|---|---|
| First EUR 250,000 | 0.5 percent |
| Next EUR 150,000 | 2 percent |
| Portion above EUR 400,000 | 3.5 percent |
The entire value is therefore not multiplied by the highest rate reached. The official overview explains the tax rates and types of acquisition.
Example without prior acquisitions to be included: For a relevant property value of EUR 500,000, the first tier results in EUR 1,250, the second in EUR 3,000 and the third in EUR 3,500. The total is EUR 7,750. This example concerns real estate and assumes that no special exemption applies.
Family Relationships: Do Not Review Only Gifts
Certain lifetime transfers between persons within the legally privileged group are treated as acquisitions without consideration for the purpose of the rate. The family relationship may therefore be relevant even if money is paid or an obligation is assumed. Privileged persons include, for example, spouses, certain cohabiting partners, relatives in the direct line, as well as siblings, nieces and nephews. The precise statutory group of persons and its requirements must be reviewed.
A close personal relationship alone is not sufficient. Provide the law firm handling the contract with complete information about the relationship between all parties. If there are several purchasers, their respective shares and requirements must be taken into account. The relevant legal basis is in particular Section 7(1) of the Austrian Real Estate Transfer Tax Act.
Partly for Consideration: When Purchase and Transfer of Value Coincide
Outside specific statutory classifications, the distinction for real estate depends on the relationship between the consideration and the property value. Up to and including 30 percent, the acquisition is treated as being without consideration. Above 30 percent and up to and including 70 percent, it is partly for consideration; above 70 percent, it is fully for consideration.
In a partly for-consideration acquisition, the part for consideration and the part without consideration are treated differently. A seemingly favourable purchase price therefore does not automatically mean that only 3.5 percent of that monetary amount is payable. The tax treatment of assumed benefits may also change the classification. The details arise from Section 7 of the Austrian Real Estate Transfer Tax Act.
Previous Transfers Within Five Years
The progressive rate is not available independently for every individual deed. Certain acquisitions without consideration between the same persons within a five-year period are aggregated. The acquisition of parts of the same economic unit from several persons may also trigger aggregation.
This does not mean that an earlier acquisition is simply taxed a second time. However, it may determine which tax tier remains available for the later acquisition. Therefore, submit previous gift and transfer agreements, even if they were handled by a different law firm. The aggregation is regulated in Section 7(1)(2) of the Austrian Real Estate Transfer Tax Act.
Property Value Is Not the Same as Asking Price
The property value is a tax base. Under the statutory rules, it may be determined, among other things, using the standardised property-value model or a suitable real estate price index. Under certain conditions, evidence of a lower common value may be provided. Section 6 of the Austrian Real Estate Transfer Tax Act contains the relevant principles.
An estate agent’s offer, a bank valuation and a tax-based property value serve different purposes. For a specific transfer, the calculation method and supporting evidence should be documented. Do not therefore adopt a figure from an older contract without checking it.
Declaration, Processing and Documents
Without self-assessment, the acquisition must generally be reported by the 15th day of the second month following the month in which the tax liability arose. Within the statutory framework, lawyers and notaries may carry out the self-assessment. The respective procedural obligations arise from Sections 10 to 13 of the Austrian Real Estate Transfer Tax Act.
For this purpose, prepare the property details, draft contract, all forms of consideration, family relationships, ownership quotas and previous transfers. Exemptions under Section 3 must be reviewed separately; neither owner-occupation nor describing the transfer as a gift creates a general tax exemption on its own.
Frequently Asked Questions
Is Real Estate Transfer Tax the Same as Real Estate Income Tax?
No. Real estate transfer tax concerns the acquisition transaction. Real estate income tax concerns income from the sale under its own requirements. The calculations must not be mixed up.
Is the Tax Waived if I Move into the Property Myself?
Having the property as your primary residence does not automatically create a general exemption from real estate transfer tax. Rules concerning land register fees must be assessed separately.
Who Should Review the Specific Calculation?
Have the tax reviewed before signing by the law firm or notary handling the transaction and consult a tax adviser if necessary. Simon Immobilien can assist with property documents and the purchase process. For this preparation, you can contact us.
This article was created with the assistance of AI. It provides solely general, non-binding information about Austrian real estate transfer tax law. It does not replace individual legal or tax advice. Contractual specifics, personal circumstances and changes in the legal framework may lead to a different assessment. No guarantee can be given as to the accuracy, completeness or applicability of the information in any specific case. Statutory liability remains unaffected.
More from Law & Taxes
- The Land Registry Consent Declaration in Austrian Property Purchases: Why Careful Review MattersRead more arrow_forward
- Foreign Landlords in Austria: Tax Liability and Double Taxation Treaties ExplainedRead more arrow_forward
- Fixed Price in Construction Contracts: When Are Extra Costs Allowed Despite a Fixed Price?Read more arrow_forward
- Right of Way by Prescription: When Neighborhood Paths Become a Legal ClaimRead more arrow_forward
Personal consultation
Questions about your property? We take the time.
Whether buying, selling, valuation or financing — let's discuss your situation in a non-binding appointment.